Handshake

Our Blog

What We're Thinking About

Updates, insights, and perspectives from the Handshake team
Handshake Finance
•
September 29, 2026

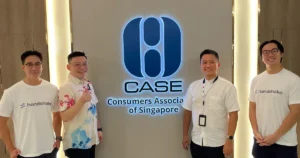
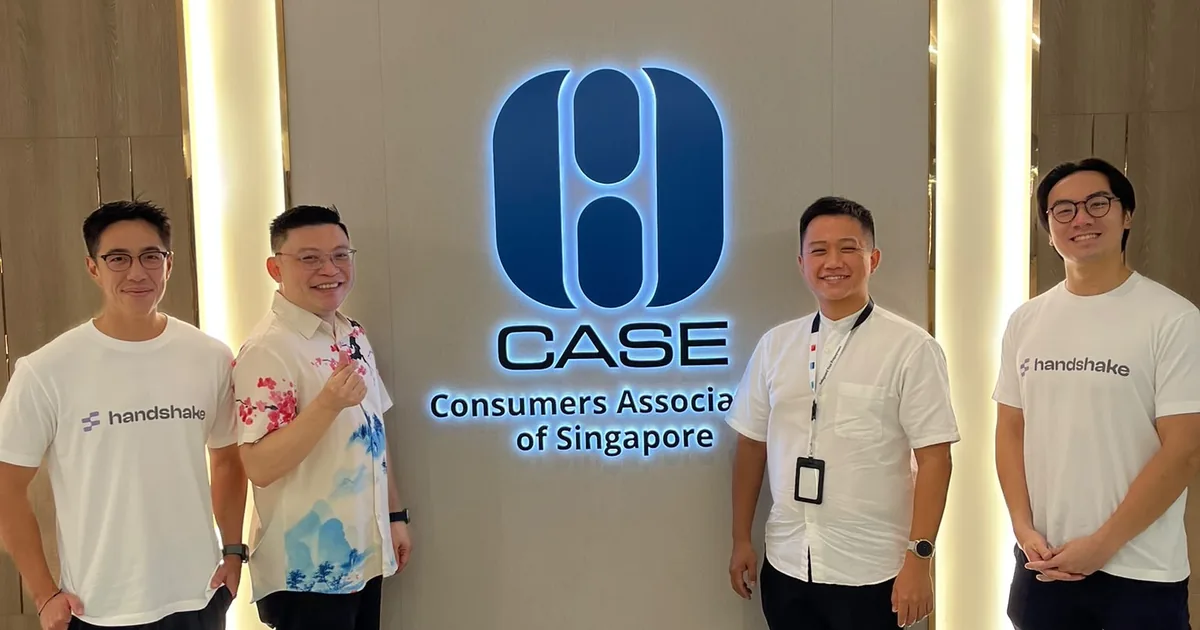
We are proud to be working closely with the Consumers Association of Singapore to make renovation payments safer for homeowners and interior designers.

CASE is a non-profit, non-governmental organisation committed to protecting consumer interests in Singapore through information, education and the promotion of fair and ethical trade practices. Home renovation is one of the biggest investments a household ever makes, and it is one of the key sectors CASE works hardest in. For good reason: almost all of a renovation is paid for before any of it is delivered.

Handshake was built for exactly that problem. We are a renovation escrow payment platform. Instead of paying your interior designer directly, you pay each stage of your renovation into an account that your interior designer cannot draw on until the work is done.

What CaseTrust accreditation already gives you

CaseTrust is the accreditation arm of CASE. Renovation businesses that are accredited are required to:

  • Buy a deposit performance bond. If the business closes, winds up or goes into liquidation before your job is done, the bond pays your deposit back.
  • Cap your initial deposit at a maximum of 20 per cent of the total contract value.
  • Collect payments in phases at agreed milestones rather than in one lump sum.

CASE currently accredits more than 300 interior design firms.

How escrow protection works with CaseTrust accredited interior designers

The deposit performance bond is solid protection for the front end of your renovation. But it covers your deposit only. With deposits capped at 20 per cent under CaseTrust accreditation, the other 80 per cent of your renovation contract is paid out in stages over the course of the project, and the bond does not extend to any of it.

That is where Handshake comes in. By working with CASE, escrow protection is now available to every homeowner hiring a CaseTrust accredited interior designer. When you pay your interior designer through Handshake, the money goes into an escrow account instead of directly to the firm. These funds get released as the work gets done and as you approve each stage.

All payments on the platform are MAS regulated. Funds are held in a custodian account with DBS.

What this looks like on an S$80,000 renovation

Say your renovation is S$80,000, split across five stages at 20, 20, 25, 25 and 10 per cent: deposit, commencement, masonry, carpentry and handover. Every CaseTrust accredited firm caps that first payment at 20 per cent.

Your deposit is held fully in escrow. You pay S$16,000 into a custodian account on Handshake and it is held securely until work is due to begin.

After that, each stage splits in half the moment you pay for it. Half goes to your interior designer, and half waits in the account until you approve that the stage is finished.

An S$80,000 renovation, stage by stage

DEPOSIT · 20%

S$16,000 in

S$16,000 held
Nothing released until work begins

COMMENCEMENT · 20%

S$16,000 in

S$8,000 released
S$8,000 held

MASONRY · 25%

S$20,000 in

S$10,000 released
S$10,000 held

CARPENTRY · 25%

S$20,000 in

S$10,000 released
S$10,000 held

HANDOVER · 10%

S$8,000 in

S$4,000 released
S$4,000 held

S$48,000 of the S$80,000 is held in escrow rather than paid out.

Across an S$80,000 renovation, S$48,000 of it is held in escrow and protected.

Why your interior designer is paid half at each stage

Renovation firms need cash to carry out your renovation, because materials and labour have to be paid for at each phase. Releasing half of each stage when you pay it in gives your interior designer the working capital to keep the project moving, so your renovation runs smoothly and on schedule.

The other half stays safely held in escrow until the work is complete and you approve the release.

See how Handshake protects your renovation payments

Does your interior designer need to be CaseTrust accredited?

No. The same escrow workflow is available whether your interior designer is CaseTrust accredited or not. Your renovation payments are held in a custodian account at DBS and released stage by stage only when you approve each one.

Once your contract is signed and before your deposit is paid, connect us with your interior designer on WhatsApp. We will get them set up in minutes.

WhatsApp us to get started

FAQ

Can an interior designer who is not CaseTrust accredited use escrow?

Yes. Handshake escrow is not limited to CaseTrust accredited firms. The split described here applies to CaseTrust accredited firms specifically. For firms outside the scheme, the full amount of every stage stays in the account until you approve that stage, which holds more of your contract. Our guide to renovation payment protection covers how that works.

Do homeowners need to pay to use Handshake?

Not at all. Handshake is completely free for homeowners. Interior designers pay a small fee which also gives them access to project and financial management tools on top of escrow protection, so there is nothing for you to pay at any point in your renovation.

See how it works for homeowners

Your renovation money held in a custodian account with DBS. Free for homeowners.
See how it works

Handshake is working with CASE to bring escrow payments to CaseTrust accredited interior designers. How your renovation money is held,
Handshake Finance
•
September 15, 2026

When you pay your interior designer, your money goes directly into their bank account. That is how almost every renovation in Singapore is paid for, one stage at a time, until the renovation is complete.

It is worth knowing what that means for your money along the way.

Once the money is in their account, they can use it however they want. Most of it pays for your materials and your labour. Some of it could also go towards their rent, their staff, or other projects they are running at the same time.

If the renovation goes well, none of this matters. In the event it does not, you have already paid for work you have not received, and getting that money back depends entirely on your interior designer agreeing to return it.

For a long time, this was the only way to pay for a renovation. There is now another way, one where your money stays out of your designer’s account until you have seen the work it is paying for. It is new to renovation in Singapore, but the mechanism itself is not new at all, and you have almost certainly used it before without knowing its name.

This guide covers what escrow is, how it works in a renovation, what it protects, and where it stops.

What escrow actually means

Escrow is an arrangement where a neutral third party holds the money until the agreed conditions are met.

You pay. The third party holds the money. The seller gets paid once the agreed work or delivery is complete. Before that, nobody can touch it.

How escrow works, step by step

1

You pay in

You transfer the stage payment to the escrow account instead of to your interior designer.

Money leaves your account

2

It is held

A neutral third party holds it while the work is done. Your designer can see it is set aside for them, but cannot take it out. Neither can you.

Money sits in escrow

3

It is paid out

You check the finished stage. When you approve it, and only then, the money goes to your designer.

Money reaches your designer

Until you approve, neither side can take the money out on their own.

That is the whole idea. Your money is set aside and clearly committed, but nobody can spend it yet.

The useful part is not that the money is held. It is that the money is only paid out for a reason, and you are the one who decides that reason has been met.

Everyday examples of escrow

The word escrow might sound new or technical. The arrangement is not. Most people in Singapore have already used it, usually without noticing.

Shopee and Lazada. When you buy something, your money does not go straight into the seller’s account. The platform holds it. The seller gets paid after you confirm the item arrived, or after the confirmation window runs out. If the item never turns up, your money is still with the platform.

Buying a home. Your deposit usually goes to a solicitor, not to the seller. It is only paid out at completion, when the property actually changes hands.

In both cases, somebody neutral holds the money, and something has to happen before it reaches the other side.

A renovation is where this matters most, and it is also where you see it least. You are paying tens of thousands of dollars, in stages, over several months, for work you cannot inspect until it exists.

Why renovation escrow works differently

Most escrow arrangements are built around one event. A property sale completes. A business changes hands. One deposit, one release, one moment.

A renovation is not one event. It is five or six. Your flat is hacked. Walls, floors and tiling go in. Carpentry is installed. Everything is painted. Defects are cleared. Each is a separate piece of work, and each is usually paid for separately.

So renovation escrow pays out in stages. Each payment is matched to a stage of work, and each payout depends on that stage being finished.

That difference matters. With a single release, you are protected right up until completion, and then the protection ends. With staged payouts, you are protected every time money leaves your side, and in a renovation that is where nearly all the risk sits.

How it works, stage by stage

You and your ID agree a payment schedule, the same as you would anyway. It sets out what gets paid at each stage, and what has to be finished before each payment is due. For what a fair schedule should contain, see our guide to renovation payment schedules in Singapore.

The only thing that changes is where your money goes.

Instead of paying each stage into your ID’s bank account, you pay it into an escrow account. Your ID can see the money is there and can start work knowing it is set aside for them. But it is not in their account yet.

When the stage is finished, your ID tells you it is ready. You check the work against what you agreed. If you are happy, you approve it and the money is paid out to your ID. If you are not, the money stays where it is until the problem is sorted out.

Point in the stage Where your money is What has to happen next
You fund the stage In the escrow account Nothing. The money is in place so work can begin
Work is underway Still in the escrow account Your ID finishes the stage
Your ID says it is done Still in the escrow account You inspect the work
You approve Paid out to your ID Your approval, and nothing else
You do not approve Still in the escrow account The problem is sorted out before any money is paid out

That last row is the one that matters.

In a normal renovation, if you are unhappy with a stage you have already paid for, your only options are to persuade your ID to come back or to chase them afterwards. With escrow, the money is still sitting in the escrow account. You decide when it is paid out, and until you do, it stays where it is.

This is how renovation payments work on Handshake, if you want to see it applied to a real payment schedule.

Who holds the money, and under what rules

This is the part worth checking on any platform you consider.

Your money should not sit in the platform’s own business account. If it does, it is mixed in with the company’s own money, and your protection depends on that company staying afloat.

On Handshake, all payments on the platform are MAS regulated. Funds are held in a custodian account with DBS.

In practice that means your money sits at a bank, in an account kept separate from Handshake’s own, and it is only paid out when the terms of the arrangement say so. Your interior designer cannot take it out. Neither can the platform.

If you are looking at any payment protection service, ask two questions. Where is my money actually held, and who is able to take it out? Anything worth using can answer both in plain language.

What escrow cannot do

Escrow does one job well. Most disappointment comes from expecting it to do a different one.

It protects your money, not the workmanship. Escrow does not inspect your tiling or check your carpentry. If a stage is done badly, escrow lets you hold the payment back until it is fixed. It will not turn a poor job into a good one. Choosing a capable interior designer is still the most important decision you make.

It only covers the payments that go through it. If you have already paid a deposit straight into your ID’s bank account, that money is theirs and escrow cannot reach it. Escrow protects what you have not paid yet, not what has already gone.

It does not decide who is right. If you say a stage is unfinished and your ID says it is done, escrow does not settle that for you. What it does is hold the money while the two of you work it out. Neither side can take it out alone, so a disagreement does not become a race for the funds. Most renovation disagreements are ordinary, a finish that is not what was agreed or a section that is nearly done, and they get settled with a conversation and a site visit.

It is not insurance. Escrow protects the money you have committed to the project. It does not cover physical damage to your home during the works, which is a separate thing entirely. For how that works, see our guide to renovation insurance in Singapore.

How Handshake does this

Handshake is a renovation payment platform for Singapore homeowners. All payments on the platform are MAS regulated, and funds are held in a custodian account with DBS.

It works the way described above. You pay each stage into escrow instead of straight into your interior designer’s bank account. Your designer can see the money is set aside and gets on with the work. When the stage is done and you approve it, the money is paid out to them.

Every milestone payment is held in full until you approve it.

You do not pay for the renovation upfront. You fund each stage when it falls due, exactly as you would now. What changes is that each of those payments goes into the escrow account rather than into your designer’s account. On an $80,000 renovation, that means all $80,000 is protected across the project, and each part of it is only paid out once you have approved the stage it belongs to.

The same five payments, two different places to sit

Paid the normal way

Each stage payment goes straight into your designer’s account as it falls due.

STAGE 1

In their bank account

STAGE 2

In their bank account

STAGE 3

In their bank account

STAGE 4

In their bank account

STAGE 5

In their bank account

Once a stage is paid, getting it back depends on your designer agreeing to return it.

Paid through escrow

Same schedule, same amounts. Each payment is held until you approve that stage.

STAGE 1

Held in escrow until approval

STAGE 2

Held in escrow until approval

STAGE 3

Held in escrow until approval

STAGE 4

Held in escrow until approval

STAGE 5

Held in escrow until approval

You approve each stage. Until you do, that payment stays in the escrow account.

Compare that with how the same renovation is normally paid. Each stage payment goes straight into your designer’s account when it falls due. By the time you are halfway through, tens of thousands of dollars have already left your hands, and getting any of it back depends on your designer agreeing to return it.

At every point in the renovation, the money for work you have not yet approved is still sitting in the escrow account rather than in your designer’s.

The exact structure is agreed for each project, and some arrangements pay out part of a stage payment earlier so your designer can fund the work. Whichever applies to yours is set out before you start, not decided along the way.

What it costs

Using escrow costs you nothing. Your interior designer pays a fee based on the transaction.

Some projects split the fee, or the homeowner covers it. That is agreed at the start rather than sprung on anyone later. But the default is that the designer pays.

Which raises a fair question. If you are not paying, why would an interior designer agree to it?

Because it solves a problem they have too.

The payments interior designers chase hardest are the handover payment and variation orders. That is the money owed once the work is finished, or once extra work has been agreed partway through. In a normal renovation those are the payments most likely to be delayed or argued over. With escrow, that money is already sitting in the account before the work starts.

A designer using escrow gets paid when you approve, rather than by chasing you. They also get a client who is more comfortable committing to a large project, because that client is not being asked to hand over large sums on trust alone.

So the protection is not free in the sense that nobody pays for it. Your interior designer pays for it, because they get something out of it too.

Keep control of your renovation payments

Every milestone held until you approve the work. Free for homeowners.

See how it works

Or ask us a question on WhatsApp

FAQ: renovation escrow in Singapore

Is renovation escrow common in Singapore?

Not yet. Most renovations are still paid straight into the interior designer’s bank account at each stage. Escrow is well established in property deals and online marketplaces, and it is newer in renovation, which is why many homeowners and designers have not come across it.

Can I use escrow if I have already paid my deposit?

Yes, for the payments you have not made yet. Escrow only covers money that goes through it, so a deposit already in your ID’s account stays where it is. If you are partway through a renovation, the remaining stages can still be set up this way. For what a normal deposit looks like and what to watch for, see our guide to renovation deposits in Singapore.

Who decides when a stage is complete?

You do. Your interior designer tells you when they think the stage is finished, and you check it against what you agreed before approving it. That is the point of the arrangement. The person paying decides when the work has been delivered.

What if my interior designer does not want to use it?

That does happen, and it is worth understanding why before deciding what to do. Some objections are practical, such as cash flow on a project already underway. Others are worth paying closer attention to, particularly a firm that will not explain its reasons.

Does escrow protect me against bad workmanship?

No. Escrow protects your money, not the quality of the work. What it gives you is the ability to hold a payment back until a problem is fixed, which is a much stronger position than asking for money back after it has been paid.

Renovating soon?

See how escrow would apply to your own payment schedule.

Protect your renovation payments

When you pay your interior designer, your money goes directly into their bank account. There is another way. This guide
Handshake Finance
•
May 19, 2026

It started with a single Instagram video on May 12, 2026. Noor Shazniah Rahmat, founder of shawls brand Kaise Store, posted about paying S$8,800 to social media agency BrandTok for 20 videos to be done by January 2026. By the end of that month, only three videos had been delivered. Four more came in February. Then nothing. She asked for a prorated refund of S$5,720. BrandTok said no, citing “legal investigations” with no further explanation.

Within 48 hours, other clients came forward with almost identical stories. Daniel Yeow of The Social Space had paid a S$5,250 deposit for a 60-video package. The videos were eventually delivered, but he described them as unusable. Captions had factual errors. The content showed no understanding of his business. He had been verbally promised a refund back in June 2025. It never came. He filed a Small Claims Tribunal claim in August. The payment arrived minutes before the October hearing.

BrandTok · Singapore · May 2026
Here’s what the numbers actually say.
12+
businesses who paid and received little to nothing in return
S$154K
combined total paid over roughly 18 months
S$39,177
in refunds requested, told the money is not currently available
1
client won S$20,600 at tribunal. As of writing, nothing has been paid.
handshake.financeSources: Mothership · The Straits Times · Marketing-Interactive

In total, at least 12 businesses paid a combined S$154,550 to BrandTok over roughly a year and a half. Individual amounts ranged from S$1,900 to S$25,000. Three businesses seeking S$39,177 in refunds have been told the money is not available.

Why this happens to Singapore SMEs

Small content agencies in Singapore often run on tight budgets. They depend on client deposits to fund current work. When they grow too fast without the right systems in place, things break down. Existing clients wait longer. New clients get signed to bring in more cash. The gap between what was paid for and what actually gets delivered keeps growing. By the time clients complain loudly enough to get attention, the money is usually already gone.

But operational problems alone don’t explain everything here. BrandTokHoldings, a new company linked to Sam Heedy, was registered in January 2026. This happened while existing client complaints were already escalating. The company kept signing new clients while failing to deliver on current ones. BrandTok’s contracts included no-refund clauses that were used to stop clients from pursuing claims they would likely have won. Verbal refund promises were made but not followed through until clients took legal action.

Bad systems and bad intentions can exist at the same time. The BrandTok story likely involves both. But here is what matters for every SME reading this: the payment structure that made this possible is the same either way. When a client has already paid in full, a failing agency and a dishonest one produce the same result. The money is gone.

The real problem is not what you think

The easy reaction is to see this as a story about one bad agency and move on. That feels safe because it suggests the fix is just better judgment about who to trust. It is not. Character is hard to assess. Payment structure is not.

When clients paid in full upfront, their money went straight into day-to-day operations. When the agency ran into trouble, there was nothing left to refund. The payment structure, not the agency’s intentions, is what left every client without any leverage. Paying everything upfront means you are financing the agency’s operations before they deliver a single thing. If anything goes wrong, for any reason, that money is already spent. You have no way to get it back.

The clients who eventually recovered money had to fight for months through legal channels. One won a tribunal judgment and still has not been paid. The payment structure put every client in a position where they were fighting for money they were already legally owed. That fight was expensive, slow, and in at least one case, still unresolved.

Payment Structure Comparison
Three structures. Three very different outcomes when things go wrong.
Full Upfront
BrandTok’s model
✕

Funds held by
The agency, immediately
✕

Payment trigger
At signing, before any work
✕

If work is poor
Limited recourse, money already spent
✕

If agency closes
Limited recourse on paid funds
✕

Your leverage
None

Milestone-Based
Better, but limited
⚠

Funds held by
The agency, per stage
✓

Payment trigger
On agreed milestone schedule
✓

If work is poor
Withhold next payment only
⚠

If agency closes
Paid tranches are lost
⚠

Your leverage
Partial

Escrow + Milestone
Structurally protected
✓

Funds held by
Independent escrow at DBS
✓

Payment trigger
Only when you approve
✓

If work is poor
Funds are held safely in escrow
✓

If agency closes
Unspent funds returned from escrow
✓

Your leverage
Full, at every stage

Before you sign: what should your per-video rate actually cover?

Most content agencies quote by volume: X videos for X dollars. That per-video rate sounds straightforward. But producing a single piece of content involves several distinct steps, each with real costs. When that rate is low, something in the list below is being cut. Usually without telling you.

Before you sign, ask the agency to confirm which of these are included in their per-video rate. A reputable agency will answer this clearly and in writing.

Before You Sign
What your per-video rate should include
If the per-video rate cannot sustain all of these at a real cost, something will be cut, usually without telling you.
Strategy and content planningPer month
Scripting and briefingPer video
Filming (crew, equipment, location)Per shoot day
Editing and post-productionPer video
Captions, subtitles and localisationPer video
Scheduling and publishingPer post
Performance reportingPer month

Ask your agency: which of these does your per-video rate include? A reputable agency will confirm this in writing before you sign.

Red flags to look out for before you sign

Most BrandTok clients had no obvious reason to suspect a problem when they signed up. The agency had a polished online presence, a well-known case study, and a confident pitch. The warning signs were in the contract terms and payment structure, not in anything visible on the surface. These are the specific things to check before committing to any agency, at any budget.

1 Full upfront payment required, with no milestone structure

Many BrandTok clients paid in full or in a large deposit before a single deliverable was completed. No payment was tied to any milestone. This is the single highest-risk term in any agency contract. Without payments tied to delivery, you have no financial leverage and no way to recover unspent funds when things fall short.

2 A per-video rate that cannot cover the full production cost

Divide the total quoted price by the number of videos. That is the effective per-video rate. Now check it against the components listed in the section above. If that rate cannot realistically cover scripting, filming, editing, captions, and reporting, something will be skipped. A low per-video rate is not a deal until you know exactly what it includes.

3 Deliverables that are not specific in writing

“60 videos” is not a scope. A proper scope specifies format, length, platform, posting schedule, approval process, revision rights, and what “completion” means for each piece of content. Daniel Yeow had no grounds to dispute work he described as unusable because the delivery standard had never been written down. If it is not in the contract with specifics, it does not exist as an enforceable obligation.

4 Case studies you cannot independently verify

BrandTok’s marketing consistently featured one campaign: the social media growth of Kucina Italian Restaurant. Chef Gero later said he was not a paid ambassador and that the results were largely driven by his own ideas. That one reference directly influenced at least one client to commit S$25,000. Before treating any case study as proof, ask to speak directly with the client featured. A real track record has more than one story. If every conversation comes back to the same name, ask why.

Once work starts: two patterns to act on immediately

5 Explanations for delays that keep changing

One BrandTok client was told delays were due to health issues. Then it became staffing problems. Then cash flow collapse. When explanations keep changing and each one is worse than the last, the agency is managing your expectations rather than the actual problem. A real operational issue comes with a revised plan. Escalating excuses without a plan are a different signal entirely.

6 Delivered work that shows no understanding of your business

Several BrandTok clients received videos with factual errors in captions, grammatical mistakes, and content that made it clear the agency had not understood their product or audience. If the first deliverable arrives that far from the brief, it is almost never a one-off problem. Raise it formally, in writing, straight away. Poor first delivery is almost always a sign of something deeper.

If it has already happened: your real options

If you are already in this situation, there are legal routes available. Each one comes with a real limitation worth understanding before you commit time and money to it.

If Things Go Wrong
Your recourse options and where each one runs out
Every path has the same core limitation: a legal ruling does not guarantee you actually get paid.
Route
What it covers
The limitation
Small Claims Tribunal (SCT)
Disputes up to S$20,000 (S$30,000 with consent). No lawyers required. Accessible to any business.
A judgment is not a payment. If the company has no assets, the ruling can’t be enforced. One BrandTok client won S$20,600. Nothing collected.

Enforcement gap
Police Report / CAD
Creates an official record. Relevant where deliberate fraud, not just poor delivery, can be evidenced across multiple victims.
Investigates criminal intent, not contract disputes. Investigations run 6 to 24 months. Does not directly recover money.

High threshold
Mediation (SMC)
Faster and cheaper than court. A neutral third party helps both sides reach a resolution.
Both parties must agree to participate. If the other side says no, it cannot proceed.

Consent required
Civil Litigation
No claim cap. You can pursue the full contract value in District Court or High Court.
Legal fees can exceed the disputed amount for smaller contracts. No contingency fee arrangements in Singapore. The same enforcement gap applies if the company has no assets.

Cost vs. recovery

All of these options share the same core problem. If there is nothing left to recover, a legal win does not mean you actually get paid. Prevention is always cheaper than the fight.

“
Businesses should be structuring milestone-based payments rather than large upfront commitments.
Affected BrandTok client
via Marketing-Interactive, May 2026

How to protect your payments to any social media agency in Singapore

The answer is not better intuition about which agencies to trust. It is removing trust from the equation entirely when it comes to money. Escrow-based milestone payments do exactly that. Your funds are committed to the project but held independently, in a custodian account, until you confirm each milestone is complete. The agency cannot access money it has not yet earned. You cannot walk away without consequence either. Both sides are accountable to the structure, not to each other’s goodwill.

This is how Handshake works. Before the project starts, you and the agency agree on a milestone schedule. Your funds go into an escrow account held at DBS, completely separate from Handshake’s own operations. When the agency completes a milestone, they notify you for review. You confirm the work is done, and the payment for that milestone releases automatically. If the milestone is not met, the funds stay in escrow. You keep the leverage to pause, renegotiate, or exit, without having already paid for work that was never delivered.

Payments through Handshake are regulated by the Monetary Authority of Singapore. Escrow accounts are held at DBS. It works the same way whether you are working with an agency you have known for years or one you are hiring for the first time. It turns every agency relationship from a trust exercise into a structural agreement. Trust still matters. It just no longer has to be the only thing standing between you and a loss.

For a complete framework on vetting any social media agency before you commit, read our guide: How to vet a social media agency in Singapore →

How it works
Handshake: Escrow + Milestone Payments for any service agreement
1
Set your
milestones
Agree what gets paid and when
2
Funds into
escrow at DBS
Held securely, not paid to agency
3
Agency
submits work
You review before anything is approved
4
You confirm,
payment releases
Your approval triggers each release

You approve every payment upon completion of agreed milestones. Works with any marketing or social media agency.
Payments are MAS RegulatedEscrow accounts held at DBSWorks with any marketing or social media agency

Handshake
Protect your payments to social media agencies.
With Handshake, funds are held at DBS and released only when you confirm each milestone is done. Works with any marketing or social media agency in Singapore.
See how it works →
WhatsApp WhatsApp us
100% free for clients
Payments are MAS RegulatedFunds held with DBSWorks with any marketing or social media agency

At least 12 businesses paid a combined S$154,550 to social media agency BrandTok. Most received little to nothing in return.
Handshake Finance
•
April 9, 2026

Many Singapore homeowners look for the CaseTrust mark when choosing a renovation firm. This guide explains what CaseTrust accreditation requires from a renovation firm, what the deposit performance bond covers and what it does not, and what homeowners need to understand about the limits of accreditation before signing anything.

What Is CaseTrust and Who Runs It?

CaseTrust is the accreditation arm of the Consumers Association of Singapore, known as CASE. CASE introduced the CaseTrust accreditation scheme recognising that home renovation represents one of the largest financial commitments most Singapore homeowners make. The scheme aims to raise industry standards by encouraging renovation firms to adopt good business practices and fair consumer policies.

CaseTrust for renovation businesses is a separate scheme from CaseTrust for e-commerce or other sectors. The CaseTrust mark on a renovation firm’s shopfront or marketing materials refers specifically to the renovation accreditation, not a general business quality standard that applies across industries.

Two types of CaseTrust renovation accreditation exist in Singapore. The first is the CaseTrust Accreditation for Renovation Businesses, for firms that are not members of the Singapore Renovation Contractors and Material Suppliers Association (RCMA). The second is the CaseTrust-RCMA Joint Accreditation, for RCMA member firms. Both schemes carry the same core obligations: the deposit performance bond and the CaseTrust Standard Renovation Contract.

What CaseTrust Accreditation Requires from a Renovation Firm

CaseTrust audits renovation firms against criteria covering four areas: policies, communication, personnel, and practices and systems. The scheme focuses on transparency, accountability, and whether a firm follows good business practices in its dealings with homeowners.

Financial requirements: Firms must purchase a deposit performance bond to safeguard homeowners’ deposit payments. They must also hold ACRA registration for at least two years before applying. This requirement filters out newly incorporated companies with no operating track record.

Operational requirements: Accredited firms must adopt the CaseTrust Standard Renovation Contract for all renovation projects. This contract specifies progressive payment schedules tied to milestones, scope of works, service warranties, and transparent pricing with itemised quotations. The contract also includes defined dispute resolution mechanisms and a 12-month workmanship warranty from the completion date of works.

Staff requirements: Firms must maintain staff training standards and demonstrate the capability to manage projects professionally. CaseTrust’s accreditation for renovation businesses aims to raise industry standards by ensuring that accredited businesses have qualified and competent personnel.

Accreditation runs for four years. CaseTrust conducts an admission audit when a firm joins and an interim audit every two years during the period. Firms pay an annual renewal fee to maintain status. CaseTrust can revoke accreditation if a firm breaches its requirements or Singapore law.

What the CaseTrust Deposit Performance Bond Actually Covers

The deposit performance bond is the most direct financial protection that CaseTrust accreditation provides to homeowners. Every accredited firm must purchase this bond. The bond is issued in the homeowner’s name. Homeowners pay nothing for it. The renovation firm pays the premium as part of its accreditation obligations.

The bond protects the deposit payment a homeowner makes against the firm’s closure, winding up, liquidation, or non-performance of the contract. After paying a deposit to a CaseTrust-accredited firm, homeowners receive proof of protection stating their details and the protected sum. Keep this document carefully.

Under the CaseTrust scheme rules, accredited renovation firms cap initial deposits at a maximum of 20% of the total renovation cost. This cap is part of the prepayment protection framework built into the accreditation scheme.

Two limits apply to the bond that most homeowners do not know about.

The bond covers the deposit only. Once the firm starts work and collects milestone payments, the bond provides no additional protection for those payments. If an accredited firm defaults mid-renovation after collecting the deposit and two subsequent milestone payments, the bond covers only the initial deposit. The milestone payments already transferred to the firm fall outside bond coverage entirely.

The bond carries a cap linked to the firm’s paid-up capital. Firms with higher paid-up capital carry a higher bond. CASE does not publish the exact cap figures, so ask the firm for the protected sum stated on your proof of protection before you pay anything. For a typical HDB renovation the deposit usually sits below the cap and the full amount is protected. On larger renovations, the cap becomes relevant.

What the bond cap means in practice

Example renovation

$80,000 total cost

Maximum deposit (20%)

$16,000

Bond covers

$16,000 deposit (if firm defaults before work begins)

Bond does not cover

$64,000 in milestone payments as work progresses

Does CaseTrust Accreditation Guarantee Workmanship Quality?

No. CaseTrust accreditation assesses a firm’s business practices and consumer policies, not the quality of its renovation work. Accreditation covers whether a firm uses proper contracts, trains its staff, maintains defined dispute resolution mechanisms, and follows transparent pricing principles. It does not assess carpentry quality, tiling standards, electrical workmanship, or any other renovation output.

CaseTrust-accredited firms must provide a minimum 12-month workmanship warranty from the completion date of works. The firm must rectify defects at its own cost during this period. This is a contractual obligation, not an insurance product. If a firm goes insolvent or refuses to honour the warranty after completion, the homeowner pursues recovery through the same formal channels available for any renovation dispute.

Accreditation does not guarantee that a firm delivers the design standard promised, meets agreed deadlines, or avoids additional costs beyond the original contract value.

How to Verify a Firm’s CaseTrust Status

To check whether a renovation firm holds current CaseTrust accreditation, search the official CaseTrust list of accredited businesses, or read the scheme requirements at case.org.sg. Do not rely on the firm’s own marketing materials, website, or verbal assurance. Accreditation can lapse or be revoked without notice to homeowners.

When checking the registry, confirm the firm’s exact registered business name matches the one on your contract and quotation. Accreditation status changes, so checking the live registry before signing or paying is the only reliable way to confirm current status. The check takes two minutes and costs nothing.

After verifying accreditation status, also check the CASE Consumer Alert List at case.org.sg for any complaints lodged against the firm. A firm may hold current accreditation while also appearing on the Consumer Alert List. Both checks are worth doing independently.

What Happens If a CaseTrust-Accredited Firm Defaults Mid-Renovation?

If a CaseTrust-accredited firm stops work, closes down, or becomes insolvent after collecting your deposit, contact CASE as soon as possible to initiate a bond claim. CASE manages the claim process for deposits made to accredited firms under the bond scheme.

The bond claim covers the deposit amount up to the cap for that firm’s paid-up capital. Milestone payments the firm collected after the deposit fall outside the bond. Recovering those payments requires the formal dispute resolution channels available to all homeowners.

The CASE complaint process can also attempt mediation between homeowners and accredited firms for disputes beyond the deposit. CASE mediation is not binding on either party. For disputes up to $20,000, or up to $30,000 where both parties sign a Memorandum of Consent, the Small Claims Tribunal provides a legal route with low filing fees and no need for a lawyer. For larger amounts, the General Division of the State Courts handles disputes but legal costs increase significantly. For a full breakdown of realistic recovery outcomes at each stage, see our guide to interior design payment in Singapore.

Beyond the Deposit: How Handshake Works Alongside CaseTrust

CaseTrust’s deposit performance bond addresses one specific risk: losing the initial deposit if an accredited firm defaults before work begins. It does not address what happens to the money homeowners pay as works progress through each renovation stage.

For a renovation costing $80,000 with a 20% deposit, the bond covers $16,000 at most. The remaining $64,000 in progressive payments carries no bond coverage. Once each milestone payment leaves the homeowner’s account and enters the firm’s, its recovery depends on the firm continuing to operate and perform.

Handshake addresses this gap. When homeowners pay through Handshake, all payment flows are fully MAS regulated, with funds held at DBS. Renovation payments do not go to the interior designer when each stage begins. The funds sit in a regulated escrow account at DBS until the homeowner confirms the previous stage is complete. The interior designer receives payment only after the homeowner approves each milestone. Any unconfirmed amount stays in the homeowner’s escrow account and the ID cannot access it.

Option 1

Non-CaseTrust firm

Deposit protection

None

Milestone payment protection

None

Workmanship warranty

No minimum required

Dispute resolution

No structured process

Option 2

CaseTrust-accredited firm

Deposit protection

Bond covers deposit only

Milestone payment protection

None once work begins

Workmanship warranty

Minimum 12 months required

Dispute resolution

CASE mediation (non-binding)

Strongest protection

Option 3

CaseTrust firm + Handshake

Deposit protection

Bond covers deposit

Milestone payment protection

MAS regulated escrow at DBS

Workmanship warranty

Minimum 12 months required

Dispute resolution

CASE mediation + Handshake process

CaseTrust accreditation and Handshake escrow address different risks. The bond covers the initial deposit. Handshake covers every milestone payment that follows.

CaseTrust accreditation and Handshake escrow are not competing mechanisms. The CaseTrust bond covers the deposit against firm default before works begin. Handshake covers every progressive payment throughout the renovation project. Using both together gives homeowners the most complete financial protection available across the full renovation journey. For a walkthrough of how this works in practice, see how your renovation money is held with Handshake and CASE.

All payment flows through Handshake are fully MAS regulated. Funds are held at DBS and released only when you approve each completed milestone.

MAS Regulated Payment Flows

·

Funds Held with DBS

Your renovation payments stay in escrow until you approve each stage.

Protect your renovation payments

FAQ: CaseTrust Renovation Singapore

Is CaseTrust accreditation mandatory for renovation firms in Singapore?
No. CaseTrust accreditation is voluntary. Singapore law does not require renovation firms to hold accreditation to operate. Accreditation signals that the firm has met the scheme’s criteria for fair consumer policies and good business practices. Most renovation firms in Singapore do not hold CaseTrust accreditation.

How much does the CaseTrust deposit performance bond cover?
The bond covers the full initial deposit amount up to a cap determined by the firm’s paid-up capital, so firms with higher paid-up capital carry a higher bond. CASE does not publish the exact cap figures, so ask the firm for the protected sum stated on your proof of protection. The bond does not cover milestone payments the firm collects once work begins.

Can I still lose money if my CaseTrust firm defaults after the deposit is paid?
Yes. The deposit performance bond covers only the initial deposit. Milestone payments the firm collects once works begin fall outside the bond. If an accredited firm defaults mid-renovation after collecting multiple progressive payments, homeowners recover those amounts only through CASE mediation, the Small Claims Tribunal, or civil court, not through the bond.

Does CaseTrust guarantee the quality of my renovation?
No. CaseTrust assesses business practices rather than renovation quality. Accredited firms must provide a minimum 12-month workmanship warranty, which is a contractual obligation requiring the firm to rectify defects at its own cost. This is different from an insurance product and depends on the firm remaining operational and willing to honour the warranty.

What is the difference between the two CaseTrust renovation accreditation schemes?
CaseTrust for Renovation Businesses is open to any renovation firm not affiliated with RCMA. CaseTrust-RCMA Joint Accreditation is for firms that hold membership with the Singapore Renovation Contractors and Material Suppliers Association. Both schemes require the deposit performance bond and the CaseTrust Standard Renovation Contract. The distinction relates to which industry body the firm belongs to rather than the level of consumer protection provided.

How do I check whether my renovation firm holds CaseTrust accreditation?
Check the official CaseTrust accredited businesses registry directly at case.org.sg. Confirm the exact registered business name matches the firm you are dealing with. Do not rely on marketing materials or verbal confirmation alone. Accreditation status can change and the live registry is the only reliable source.

CaseTrust accreditation provides homeowners with specific protections: a deposit performance bond covering the initial deposit, a requirement to use the standard renovation contract with progressive payment schedules, transparent pricing, defined dispute resolution mechanisms, staff training standards, and a minimum 12-month workmanship warranty. Understanding precisely what these protections cover and where they stop allows homeowners to make informed decisions about how to structure payments and what additional protection they need throughout the full renovation project.

For homeowners who want protection that extends to every milestone payment throughout the renovation, see our guides to renovation deposits in Singapore, renovation payment schedules, and interior design payment in Singapore.

All payment flows through Handshake are fully MAS regulated. Funds are held at DBS and released only when you approve each completed milestone.

MAS Regulated Payment Flows

·

Funds Held with DBS

Every milestone. Every payment. Protected until you say so.

Get started with Handshake

CaseTrust accreditation provides a deposit performance bond, a standard contract, and access to CASE mediation. This guide explains exactly what
Handshake Finance
•
April 7, 2026

Most Singapore homeowners think about insurance at the wrong time. After something goes wrong. This guide explains the two types of insurance relevant to any Singapore renovation, who is responsible for each, and the one financial risk that neither covers.

What “Renovation Insurance” Actually Means in Singapore

There is no single product in Singapore called “renovation insurance.” What exists are two separate insurance mechanisms that apply at different stages of your renovation, held by different parties, covering different risks.

Understanding this distinction before your renovation begins is the most important thing this guide can help you with. Conflating the two is the reason most homeowners end up either underinsured, overinsured, or insured for the wrong thing entirely.

The Two Types of Insurance Every Singapore Homeowner Needs to Understand

The first is Contractor’s All Risks insurance, known as CAR insurance. This is a short-term construction-period policy that covers accidental damage and third-party liability during the active renovation works. It is typically taken out by your interior designer or renovation contractor, not by you. It is required before your contractor can obtain an HDB renovation permit, and most MCSTs require proof of it before approving condo renovation applications.

The second is home insurance with a renovation add-on. This is a long-term policy that you hold as the homeowner. It covers your completed renovations against future damage events including fire, burst pipes, flood, and theft, after your renovation is finished and you are living in your home. This is what products like AIG Homes Essential, Singlife Home Plus, Income Enhanced Home Insurance, and FWD Home Insurance provide. These policies protect your completed renovation from future damage. They do not cover accidental damage during active construction works.

These are not interchangeable. CAR insurance protects during works. Home insurance protects after works. Understanding which applies at which stage is the foundation of proper renovation protection.

During renovation works

CAR Insurance

Who holds it

Your contractor or ID

What it covers

Accidental damage during works, third-party liability, worker injury

Required by

HDB (for renovation permit), most MCSTs

When active

From start of works until completion

After renovation completes

Home Insurance

Who holds it

You as the homeowner

What it covers

Completed renovations against fire, burst pipes, flood, theft after you move in

Required by

Not compulsory by law; banks may require it for renovation loans

When active

Ongoing annual policy while you live in the home

Is There a Separate “Renovation Insurance” Product in Singapore?

Some sources use the phrase “renovation insurance” loosely to describe CAR insurance or a homeowner renovation rider. To be precise about what is available in Singapore in 2025, there are distinct products for each phase.

For the construction period, the product is Contractor’s All Risks (CAR) insurance. This is typically purchased by your contractor or ID. Income Insurance offers a Renovation Contractor Suite specifically for interior renovation works, covering accidental damage and third-party liability. AIG offers a Specialty Contractors and Renovators Scheme covering WICA and public liability for renovation contractors. These are commercial products purchased by businesses, not homeowners.

For the post-renovation period, major Singapore insurers including AIG, Singlife, Income, FWD, Great Eastern, and Etiqa offer home insurance plans with renovation coverage as a standard inclusion or add-on. Renovation sum insured under these plans can typically be set up to $150,000 to $200,000. Most plans also include home assistance services covering emergency plumbing, electrical, locksmith, and aircon repairs, typically up to $150 per visit, up to three times per year. This is a separate benefit from renovation coverage itself.

What you as a homeowner need to understand is that the product covering your active renovation period is your contractor’s responsibility to hold. Your responsibility is to verify they hold it before works begin, and to hold your own home insurance to protect your completed renovations after you move in.

Is CAR Insurance Compulsory in Singapore?

For HDB flats, insurance meeting minimum coverage limits set by HDB is required before your contractor can obtain an HDB renovation permit. This is not optional. Without proof of insurance, no permit is issued, and without a permit, no legal renovation works can begin. The minimum public liability coverage for most HDB renovation projects starts at $50,000, though exact requirements depend on the scope of works.

For condominiums under an MCST, most management offices require a valid Certificate of Insurance from your contractor as part of the renovation application. Requirements vary by development. Some MCSTs require higher public liability limits up to $250,000, particularly for developments with premium finishes in common areas. In addition, MCSTs typically require a refundable security deposit of $500 to $5,000 to cover potential damage to common property.

For landed properties, there is no central mandate but the risk exposure is typically higher due to outdoor interface and shared boundaries. Higher liability and CAR coverage than a typical HDB project is advisable.

Who Is Responsible for CAR Insurance

Your contractor or interior designer is the primary policyholder for CAR insurance during renovation works. In Singapore, renovation insurance policies are usually only taken out by interior designers or contractors. Under Singapore’s Work Injury Compensation Act, contractors are also legally required to hold appropriate WICA coverage for their workers on site.

However, being the primary policyholder and protecting your interests as the homeowner are not the same thing. If you are not named as an insured or interested party on your contractor’s CAR policy, your claim rights are indirect. This means if something goes wrong, you are relying on your ID to pursue the claim, which is slower and more complicated, particularly if the contractor’s policy has lapsed or subcontractors are not covered.

Before any works begin, ask your interior designer for a copy of their Certificate of Insurance. Confirm it covers the full period of your renovation. Check that you are named or listed as an interested party on the policy. When in doubt, call the insurer’s customer service line directly to verify the policy is active before works begin. If your MCST specifically requires a policy in your name, your contractor’s COI alone may not be sufficient. Check with your building management before work starts.

Red flags — ask before signing

✗

ID cannot produce a Certificate of Insurance on request

✗

Policy has already expired or does not cover your full renovation period

✗

Coverage limits significantly below HDB or MCST minimums

✗

Subcontractors not named or covered under the main policy

What CAR Insurance Covers During Your Renovation

Standard CAR insurance in Singapore during renovation works covers three main areas.

Third-party liability is the most important component. If your renovation works accidentally damage a neighbour’s property, cracking their ceiling during hacking, causing water seepage through a shared wall, or scratching a lift panel during debris removal, the third-party liability component covers the compensation and claim costs. This is the component HDB and MCSTs make mandatory because dense Singapore living means a single renovation accident can affect multiple households.

Accidental damage to works in progress covers renovation materials and structures on site if accidentally damaged during works. If tiles on site are accidentally broken or a pipe is severed during hacking, this component covers reinstatement costs.

Worker injury coverage under WICA protects against compensation claims if a worker is injured during renovation works in your home. Your contractor is legally required to hold this under Singapore’s Work Injury Compensation Act. If they do not, liability can fall back on you as the homeowner.

What Home Insurance Covers After Your Renovation

Once your renovation is complete and you move in, your home insurance policy takes over. A standard home insurance policy with renovation coverage covers your completed renovations, including cabinets, built-in fixtures, flooring, and fittings, against named perils including fire, burst or overflowing water pipes, flood, theft, and other specified damage events.

This is a separate product from HDB fire insurance. HDB fire insurance is compulsory for all HDB flat owners with an outstanding HDB housing loan, and covers only the cost of reinstating building structures, fixtures, and fittings built and provided by HDB in the event of a fire. It does not cover your renovations, furniture, personal belongings, or any damage during or after renovation works. It is not a substitute for home insurance.

Home insurance fills that gap. It is not compulsory under Singapore law for most homeowners, though banks granting home loans may require it as a condition of the loan. It is strongly recommended as the cost, typically $75 to $243 per year for standard plans, is a small fraction of what a single water damage or fire claim could cost.

Standard policies also exclude wear and tear. Gradual deterioration of renovation materials over time is not a claimable event under any home insurance plan. This is consistent across all major Singapore insurers.

What Neither Type of Insurance Covers

This is the section every homeowner should read before signing anything with an interior designer.

Not covered by any insurance

Contractor insolvency or absconding

If your interior designer takes your deposit and disappears, or the company is wound up mid-project, no insurance policy pays you back. This is a commercial failure, not an accidental physical event. Insurance is a physical-risk product.

Not covered by any insurance

Poor workmanship and defects

If your renovation is completed but the tiling is uneven, carpentry poorly fitted, or finishes do not match what was agreed, no insurance policy covers this. Workmanship is explicitly excluded from all standard renovation insurance in Singapore.

Not covered by any insurance

Your renovation deposit if work never starts

If you pay a deposit and your ID defaults before hacking begins, there is no mainstream insurance product in Singapore that covers this specific financial loss. Neither HDB nor MAS requires renovation insurance to include deposit protection.

Not covered by any insurance

Cost overruns and delays

If your renovation goes over budget, runs past the agreed timeline, or your ID raises variation orders beyond what you budgeted, insurance does not apply. These are contractual matters between you and your ID, not insured events.

Understanding these exclusions matters because the financial risks that most homeowners fear, losing their deposit, paying for a renovation never finished, or being left with substandard work, are precisely what insurance was never designed to address.

How Much Does CAR Insurance Cost in Singapore?

CAR insurance premiums in Singapore in 2025 start from around $50 for a basic third-party liability only plan and can reach $500 or more for comprehensive coverage on a full home renovation. All premiums are subject to 9% GST.

For a typical 4-room HDB renovation at around $45,000 to $55,000 in total contract value, expect to pay roughly $200 to $350 for a standard CAR policy with adequate third-party liability coverage. For larger renovations or condominiums requiring higher liability limits, premiums of $500 to $850 or more apply for contract values approaching $100,000.

Renovation scope Contract value Typical CAR premium Minimum TPL coverage
Light refresh (painting, minor carpentry) Under $20,000 $50 to $100 $50,000
3-room HDB full renovation $25,000 to $40,000 $150 to $250 $50,000
4 to 5-room HDB full renovation $45,000 to $75,000 $200 to $350 $50,000 to $100,000
Condo full renovation $80,000 to $120,000 $400 to $600 $100,000 to $250,000
Large renovation or landed property Above $120,000 $600 to $850+ $250,000+

Figures are indicative market ranges for 2025. All premiums subject to 9% GST. Always request at least two quotes with equivalent coverage limits before purchasing.

What Renovation Insurance Cannot Protect — And What Does

The gap in every insurance product described above is the same. Once your renovation payment leaves your account and enters your ID’s, no insurance policy protects it.

CAR insurance and home insurance both address physical risk, including accidental damage, third-party liability, fire, and flood. The financial risks of renovation, including deposit loss, contractor default, payment disputes, and incomplete works, fall entirely outside what any renovation insurance product in Singapore covers.

The mechanism that addresses financial risk directly is a regulated payment escrow. When you pay through Handshake, all payment flows are fully MAS regulated, with funds held at DBS.

Your renovation payments do not go to your ID when each stage begins. They sit in a regulated escrow account at DBS until you confirm each stage is complete to your satisfaction. Your ID gets paid only after you approve each milestone. Any amount not yet confirmed stays in your escrow account and cannot be accessed by your ID.

Homeowner

Puts funds into Handshake escrow before each milestone

→

funds

Handshake escrow

Held at DBS until you confirm

All flows MAS regulated

→

on confirmation

Interior designer

Gets paid only after you confirm each stage is complete

✓

You confirm the stage. Funds go to your ID and the next stage begins.

✗

Dispute raised. Funds stay in escrow while the resolution process is followed.

This means the scenario that no insurance covers, your ID stopping work, defaulting, or disappearing with your money, is the exact scenario Handshake is designed to prevent. Because the funds have not yet left your hands, there is nothing to recover. The risk never materialises.

CAR insurance, home insurance, and Handshake escrow address different risks at different stages. CAR covers accidents during works. Home insurance covers your completed renovation against future damage events. Handshake covers your money throughout the project. Used together, they give you the most complete protection available to a Singapore homeowner during renovations.

All payment flows through Handshake are fully MAS regulated. Funds are held at DBS and released only when you approve each completed milestone.

MAS Regulated Payment Flows · Funds Held with DBS

Your renovation payments stay in escrow until you approve each stage.

Protect your renovation payments

If Something Goes Wrong: Your Legal Recourse Options

If a dispute arises during your renovation, these are the formal channels available to Singapore homeowners.

File a complaint with the Consumers Association of Singapore (CASE). CASE can attempt mediation between you and your ID. If your ID is CaseTrust-accredited, CASE can initiate a claim under the deposit performance bond for the initial deposit. Mediation is not binding on either party but creates a formal record. For a detailed guide to how CASE, the Small Claims Tribunal, and civil court work in renovation disputes, see our guide to interior design payment in Singapore.

The Small Claims Tribunal handles disputes up to $20,000 with low filing fees and no need for a lawyer. Outcomes typically take 2 to 4 months. For disputes above $20,000, the General Division of the State Courts handles it but legal costs rise significantly.

For renovation scam situations where your ID has taken payment with clear intent to defraud, a police report is appropriate in addition to the above. See our guide to renovation scams in Singapore for the full first 48 hours process.

FAQ: Renovation Insurance Singapore

Is renovation insurance the same as home insurance?
No. These are two different products for two different stages. During active renovation works, the relevant product is Contractor’s All Risks (CAR) insurance, typically held by your contractor. It covers accidental damage and third-party liability during construction. After your renovation is complete, your home insurance policy with a renovation add-on covers your completed renovations against future events like fire, burst pipes, and theft. Your standard home insurance does not cover accidents during active construction works.

Does my HDB fire insurance cover my renovation?
No. HDB fire insurance is compulsory for HDB flat owners with an outstanding HDB housing loan. It covers the cost of reinstating building structures, fixtures, and fittings built and provided by HDB if damaged by fire. It does not cover your renovations, home contents, personal belongings, or any damage during renovation works. Separate home insurance is required to cover your completed renovations after you move in.

Who is responsible for CAR insurance during my renovation?
Your interior designer or contractor is the primary policyholder for CAR insurance. They are legally required under Singapore’s Work Injury Compensation Act to hold WICA coverage for their workers. Before works begin, ask your ID for their Certificate of Insurance and check that you are named as an interested party on the policy. If you are not named, your claim rights are indirect if something goes wrong.

What happens if my contractor damages my neighbour’s flat during renovation?
The third-party liability component of your contractor’s CAR insurance covers accidental damage to neighbouring units or common property. This is why HDB and most MCSTs require proof of insurance before renovation permits are issued. If the damage results from poor workmanship rather than an accident, the claim may be denied under standard workmanship exclusions.

Can I claim insurance if my ID disappears mid-project with my money?
No. Contractor insolvency, absconding, or deposit loss are commercial failures, not accidental events. No CAR insurance or home insurance product in Singapore covers these scenarios. A MAS-regulated payment escrow, where funds are held at DBS and released only on your approval, is the protection designed specifically for this risk.

Is my renovation deposit protected if my contractor goes bankrupt?
No. Your renovation deposit is not protected by any insurance product in Singapore’s mainstream market. If your contractor is wound up, recovering your deposit requires formal legal process. Recovery is not guaranteed. A regulated payment escrow prevents this scenario by ensuring your deposit sits at DBS and never moves to the contractor’s account until you confirm the work is done.

What is the difference between CAR insurance and home insurance for renovations?
CAR insurance is a short-term construction-period policy covering accidental damage and third-party liability during active renovation works. It is held by your contractor, required for HDB permits and most MCST approvals, and active from when works begin until completion. Home insurance with a renovation add-on is a long-term policy you hold as the homeowner, covering your completed renovations against future damage events like fire, burst pipes, and theft after you move in. Both are necessary. Neither covers contractor default or deposit loss.

Renovation insurance in Singapore is not one thing. It is two things, a construction-period product held by your contractor, and a long-term home protection product held by you. Understanding which applies at which stage, and knowing what neither covers, is the difference between a homeowner who is protected and one who only thinks they are.

All payment flows through Handshake are fully MAS regulated. Funds are held at DBS and released only when you approve each completed milestone.

MAS Regulated Payment Flows · Funds Held with DBS

Every milestone. Every payment. Protected until you say so.

Get started with Handshake

There is no single product called "renovation insurance" in Singapore. There are two — one held by your contractor during
Handshake Finance
•
April 3, 2026

Every year, Singapore homeowners suffer significant financial losses from renovation fraud. Some lose their deposit before a single wall is hacked. Others pay progressively, only for their ID to disappear halfway through. In almost every case, the warning signs were there before the first payment was made.

This guide covers how to identify a renovation scam before you sign anything, how to vet your interior designer properly, what to do in the first 48 hours if things go wrong, and why the difference between a scam and poor workmanship changes everything about your options.

What Is a Renovation Scam in Singapore — and What Is Not

Before you can protect yourself from a renovation scam, you need to understand what one actually is. This distinction matters because it determines which authority you contact, what evidence you need, and what recovery is realistic.

A renovation scam involves deliberate intent to defraud. The interior designer or renovation company takes your money without ever intending to complete the work. Common patterns include collecting a large deposit and disappearing, using a fake or borrowed portfolio to win the job, operating under a shell company with no real capacity to renovate, and rebranding after complaints by registering a new company under a different name.

Poor workmanship is different. Your ID completes the renovation but the quality is substandard — tiles are uneven, cabinets are poorly fitted, or promised finishes do not match what was delivered. This is a contractual dispute, not a criminal matter. Your recourse options are different and so is the process for pursuing them.

The distinction matters because a police report is only appropriate for criminal fraud, not workmanship disputes. Filing a police report against an ID who delivered poor tiling does not help you and wastes time you could spend pursuing the right channel.

How to Tell the Difference Before It Is Too Late

Most renovation scams follow recognisable patterns. Here is what to watch for before you sign anything.

Warning sign 1

Quote 25 to 40% below every other firm

A quote that is far below market rate for the same scope is not a bargain. It is either a loss-leader to secure the deposit or a sign the company lacks the capacity to deliver. Legitimate interior design firms in Singapore price within a predictable range for a given scope of work.

Warning sign 2

Large upfront deposit demand

The industry norm for an initial deposit in Singapore is 10 to 20% of the total renovation cost. Any demand for 30%, 40%, or 50% upfront before work begins is a significant red flag. For the full breakdown of what a safe deposit looks like by flat type, see our guide to interior design payment in Singapore.

Warning sign 3

Cash only or personal bank account

All legitimate payments should go to the interior design firm’s registered company account. A personal bank account has no legal connection to the business. Cash leaves no paper trail. If your ID cannot accept a bank transfer to a business account and issue an official receipt, do not proceed.

Warning sign 4

Vague or verbal contract

A legitimate renovation contract in Singapore is detailed. It itemises the scope of work, materials, timeline, payment schedule tied to milestones, and variation order process. If your ID resists putting things in writing or sends a one-page summary and calls it a contract, that is a warning sign.

Warning sign 5

Portfolio cannot be verified

Ask for the addresses of two or three completed projects and request permission to contact the previous homeowners. A legitimate ID with a genuine track record will have no problem with this. Resistance to portfolio verification is one of the strongest pre-signing warning signs you will encounter.

Warning sign 6

Newly registered company with very low paid-up capital

You can check any Singapore company’s registration status, paid-up capital, and director history on ACRA BizFile+ at no cost. A company incorporated less than 12 months ago with paid-up capital below $10,000 is a meaningful risk signal — not disqualifying on its own, but worth noting alongside other flags.

The 5 Non-Negotiable Checks Before You Pay Anything

These checks take less than 30 minutes in total. Do all five before signing a contract or transferring any money.

Check 1: ACRA BizFile+
Go to bizfile.acra.gov.sg and search the company name. Confirm the company is active, note the date of incorporation, check the paid-up capital, and look at the director’s history. If a director appears on multiple recently dissolved companies, that is a serious flag requiring follow-up.

Check 2: HDB Licensed Contractor List
For HDB home renovations, your ID must be on HDB’s Directory of Renovation Contractors. Check at hdb.gov.sg. An unlicensed contractor doing HDB work creates liability for you as the homeowner and signals the firm is operating outside proper channels.

Check 3: CaseTrust Accreditation
CaseTrust accreditation requires interior design firms to follow fair payment schedule practices and hold a deposit performance bond. Check the official list at case.org.sg. If your ID is CaseTrust-accredited, the bond provides some protection on the initial deposit if they default before work begins. It does not cover workmanship disputes or payments made after work starts.

Check 4: CASE Consumer Alert List
The Consumers Association of Singapore (CASE) maintains a Consumer Alert List of businesses that have received complaints from consumers. Search your ID’s company name at case.org.sg before signing anything.

Check 5: Portfolio Verification
Ask for 2 to 3 project addresses and the homeowners’ contact details. Visit one if possible. If you cannot visit, ask for video walkthroughs or contact the previous homeowners directly. A legitimate interior designer will welcome this. An ID who deflects or refuses has something to hide.

What to Do in the First 48 Hours If You Suspect a Scam

If your ID has stopped responding, disappeared, or you believe you have been defrauded, these are the steps to take immediately.

Stop all further transfers. Do not send any additional money regardless of what your ID says. If they claim they need more funds to continue or threaten to abandon the project, do not pay. Any payment made after the red flags appear is money you are unlikely to recover.

Document everything immediately. Screenshot every WhatsApp message, email, and payment receipt. Photograph the current state of your home. Print or save a copy of your contract. This documentation is the foundation of every formal route that follows.

Reach your ID in writing. Send a WhatsApp message and email stating clearly that you have not received the agreed work, you are concerned, and you expect a response within 24 hours. This creates a formal paper trail and establishes the date you raised your concerns.

File a complaint with CASE. Go to case.org.sg or call the CASE hotline. If your ID is CaseTrust-accredited, CASE can initiate a claim under the deposit performance bond for the initial deposit. If your ID is not CaseTrust-accredited, CASE can still attempt mediation — though it is non-binding. Creating this formal record quickly is important.

Consider a police report if there is clear evidence of fraud. A police report is appropriate when there is clear intent to defraud — the company does not exist at the registered address, the portfolio was fabricated, or the ID collected multiple deposits and disappeared. A police report opens a criminal investigation. It does not directly recover your money but it does establish a criminal record if the investigation succeeds.

For disputes up to $20,000, or up to $30,000 where both parties sign a Memorandum of Consent, the Small Claims Tribunal is accessible and affordable. For amounts above $20,000, the General Division of the State Courts handles it but legal costs rise significantly. For a full picture of what realistic recovery looks like at each stage and what the honest recourse options are, see our guide to interior design payment in Singapore.

The Honest Reality About Recovery

The homeowners who recover money after a renovation scam are those who acted quickly, had a paper trail, and had not already paid out most of the contract value. The homeowners who suffer the greatest financial losses are those who continued paying after the first warning signs appeared.

Recovery through CASE mediation, the Small Claims Tribunal, or civil court is possible — but it is not guaranteed, it takes time, and it requires the company to still be a legal entity. If the renovation companies involved have dissolved their registration, your civil claim has no legal entity to attach to. Pursuing individual directors personally is complex and expensive.

This is not pessimism. It is the accurate picture that every formal legal channel in Singapore will give you if you ask. Prevention is the only genuinely reliable protection available to homeowners in Singapore renovations today.

How Handshake Protects You From the Moment You Pay

The gap in every protection described above is the same. Once your money leaves your account and enters your ID’s, you have lost control of it. Every recourse option — CASE, the Small Claims Tribunal, civil court — is about trying to recover money that has already gone.

Handshake closes that gap. When you make renovation payments through Handshake, all payment flows are fully MAS regulated, with funds held at DBS.

Your renovation funds do not go to your ID when each stage begins. They sit in a regulated escrow account at DBS until you confirm the previous stage is complete to your satisfaction. Your ID gets paid only after you approve each completed milestone. Any amount not yet confirmed stays in your escrow account and cannot be accessed by your ID.

Homeowner

Puts funds into Handshake escrow before each stage begins

→

funds

Handshake escrow

Held at DBS until you confirm

All flows MAS regulated

→

on confirmation

Interior designer

Gets paid only after you confirm each stage is complete

✓

You confirm the stage — funds go to your ID and the next stage begins

✗

Dispute raised — funds stay in escrow while the resolution process is followed

If a dispute arises, the money in question has not already left your hands. That changes your position fundamentally compared to having already paid and then pursuing recovery through formal channels.

Handshake works with any interior designer in Singapore, CaseTrust-accredited or not. If your ID is CaseTrust-accredited, Handshake and the deposit performance bond work together to give you the strongest available protection at every stage. If your ID is not CaseTrust-accredited, Handshake is your primary protection from the first payment to the last.

All payment flows through Handshake are fully MAS regulated. Funds are held at DBS and released only when you approve each completed milestone.

Protect your renovation from scams with Handshake

FAQ: Renovation Scams in Singapore

How do I know if my interior designer is legitimate?
Run the five checks before signing anything: ACRA BizFile+ for company registration and director history, HDB licensed contractor list for HDB flats, CaseTrust accreditation status on case.org.sg, CASE Consumer Alert List, and portfolio verification by contacting previous homeowners directly. A legitimate ID passes all five without hesitation.

What is the difference between a renovation scam and poor workmanship?
A renovation scam involves deliberate intent to defraud — collecting money without ever intending to complete the work. Poor workmanship means the renovation was completed but the quality is substandard. The distinction determines whether criminal law applies, which authority to contact, and what recovery is realistic. Police reports are appropriate for fraud. CASE and the Small Claims Tribunal handle workmanship disputes.

What should I do if my interior designer disappears with my deposit?
Stop all further transfers immediately. Document every payment receipt, message, and contract. File a complaint with the Consumers Association of Singapore (CASE) as soon as possible. If your ID is CaseTrust-accredited, CASE can initiate a claim under the deposit performance bond. For disputes up to $20,000, or up to $30,000 where both parties sign a Memorandum of Consent, the Small Claims Tribunal is accessible and affordable. A police report is appropriate if there is clear evidence of criminal fraud.

Is CaseTrust accreditation enough protection against renovation scams?
CaseTrust accreditation provides meaningful protection through the deposit performance bond, which covers the initial deposit if your ID defaults before work begins. It does not cover milestone payments made after work starts, poor workmanship, or disputes with non-CaseTrust firms. For full protection at every stage, using a payment platform where funds are held in regulated escrow at DBS provides a level of protection the bond alone cannot match.

How much deposit should I pay a Singapore interior designer?
The safe maximum is 20% of the total renovation cost. For a $50,000 renovation, that is $10,000. Any demand above 20% before work begins is a red flag. For the full breakdown by flat type and what progressive payments should look like across all stages, see our guide to interior design payment in Singapore.

Can I recover my money through the Small Claims Tribunal?
Yes, for disputes up to $20,000. The filing fee is low and you do not need a lawyer. The process typically takes 2 to 4 months. For amounts above $20,000 the General Division of the State Courts applies and legal costs rise significantly. Recovery depends on the company still being a legal entity — if the renovation companies involved have dissolved their registration, enforcement becomes significantly harder.

Renovation scams in Singapore are preventable. The homeowners who lose money are not those who lacked information — they are those who skipped the checks, ignored the warning signs, or continued paying after the first red flags appeared. The checks take 30 minutes. The consequences of skipping them can take months and thousands of dollars to undo.

All payment flows through Handshake are fully MAS regulated. Funds are held at DBS and released only when you approve each completed milestone.

Protect your renovation from scams with Handshake

Renovation scams in Singapore follow predictable patterns. This guide covers the warning signs before you sign, the red flags once

All blog posts

Recent blog posts

Scroll to Top